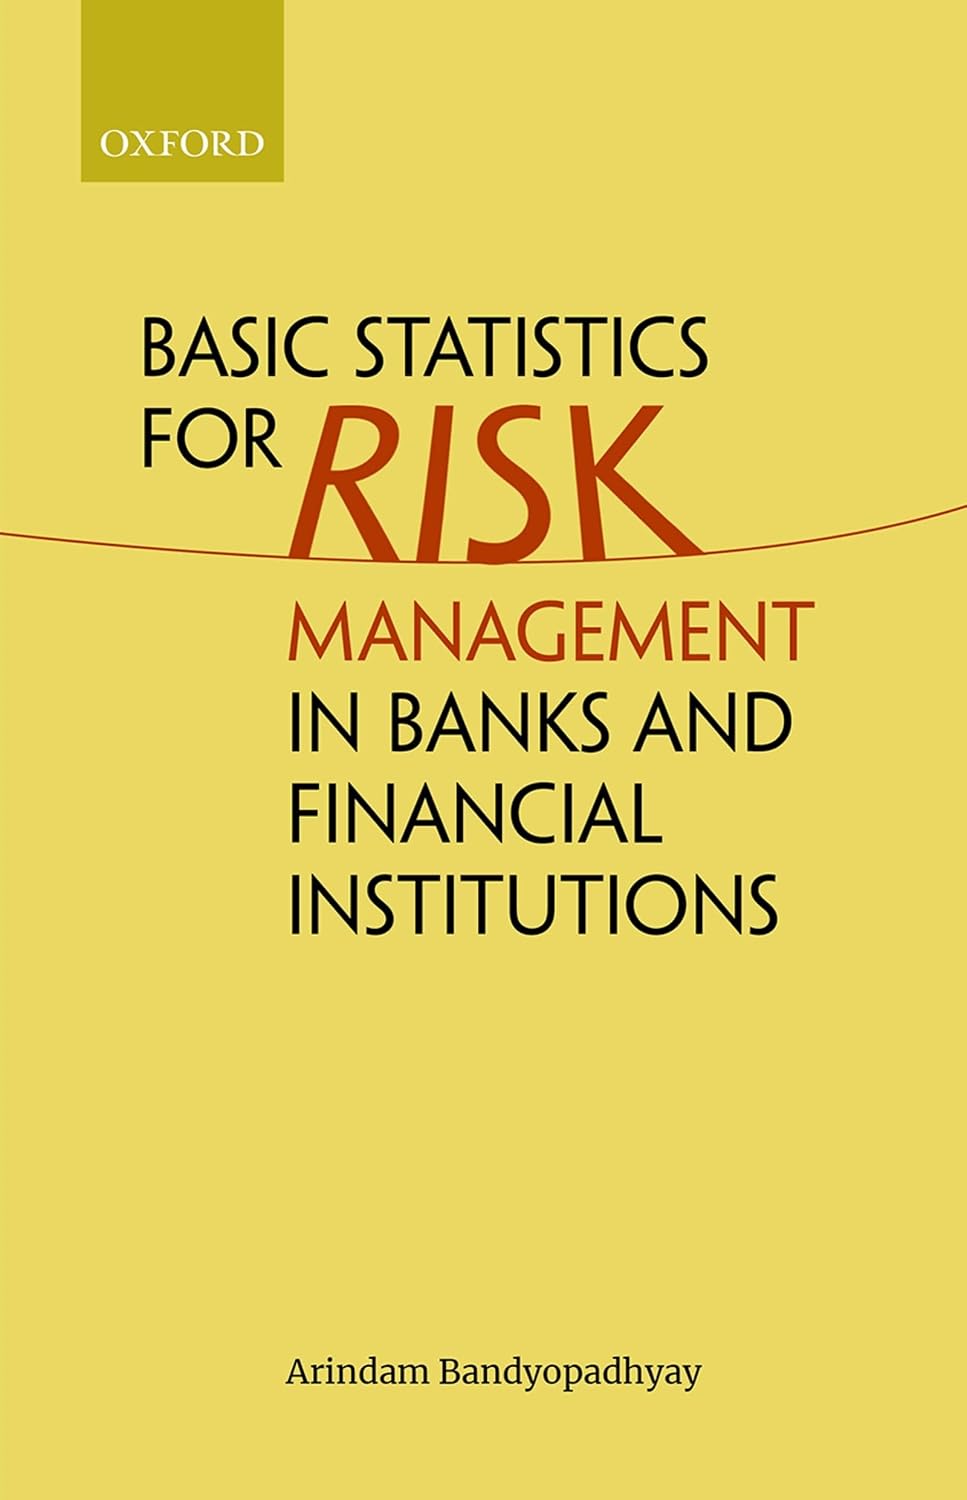
ler totalmente Basic Statistics for Risk Management in Banks and Financial Institutions
por Associate Professor (Finance) Arindam Bandyopadhyay
Basic Statistics for Risk Management in Banks and Financial Institutions
The book provides an engaging account of theoretical, empirical, and practical aspects of various statistical methods in measuring risks of financial institutions, especially banks. In this book, the author demonstrates how banks can apply many simple but effective statistical techniques to analyze risks they face in business and safeguard themselves from potential vulnerability. It covers three primary areas of banking; risks-credit, market, and operational risk and in a uniquely intuitive, step-by-step manner the author provides hands-on details on the primary statistical tools that can be applied for financial risk measurement and management. The book lucidly introduces concepts of various well-known statistical methods such as correlations, regression, matrix approach, probability and distribution theorem, hypothesis testing, value at risk, and Monte Carlo simulation techniques and provides a hands-on estimation and interpretation of these tests in measuring risks of the financial institutions. The book strikes a fine balance between concepts and mathematics to tell a rich story of thoughtful use of statistical methods.
Procurando Basic Statistics for Risk Management in Banks and Financial Institutions? Aqui você encontra tudo sobre este livro de Associate Professor (Finance) Arindam Bandyopadhyay, publicado por Oxford University Press em 19 de dezembro de 2022. Nesta página estão a descrição da obra, os detalhes da edição (314 páginas) e os formatos disponíveis para baixar: pdf, epub, txt, djvu. Se você gosta de Livros Internacionais, Administração, Negócios e Economia, Economia, Estatísticas, explore também outros títulos da mesma categoria no Encontrando os melhores livros. Veja ainda as outras obras de Associate Professor (Finance) Arindam Bandyopadhyay em nosso catálogo.
Autores populares
Icon Group International (283) Publishing lmgdaw (250) Nikolay Krechet (145) Kennie B Journals (120) Charles Nehme (106) Riddler Books (105) webmarbook design (103) Mint and Cherry Notebooks (82) Jillo Trukudo (80) Ondrej Sarek (76) Iwona Makara (74) Just Visualize It (71) Moonpeak Library (69) Quick Witted Coconut (69) Various (68) Mary Hirose (67) Talor Press (67) Marina Buchholz B.Eng (58) Miller Sye (58) NAK Legal Publishing (58)Principais publicadores
Independently published Forgotten Books Routledge Oxford University Press Taschen Dover Publications Wiley CRC Press Kessinger Publishing Princeton University Press Cambridge University Press Springer Bloomsbury Academic O'Reilly Media Hal Leonard Publishing Corporation Tuttle Publishing Rizzoli International Publications Content provided by MemoryLane.com Editorial Tirant lo Blanch Thames & Hudson