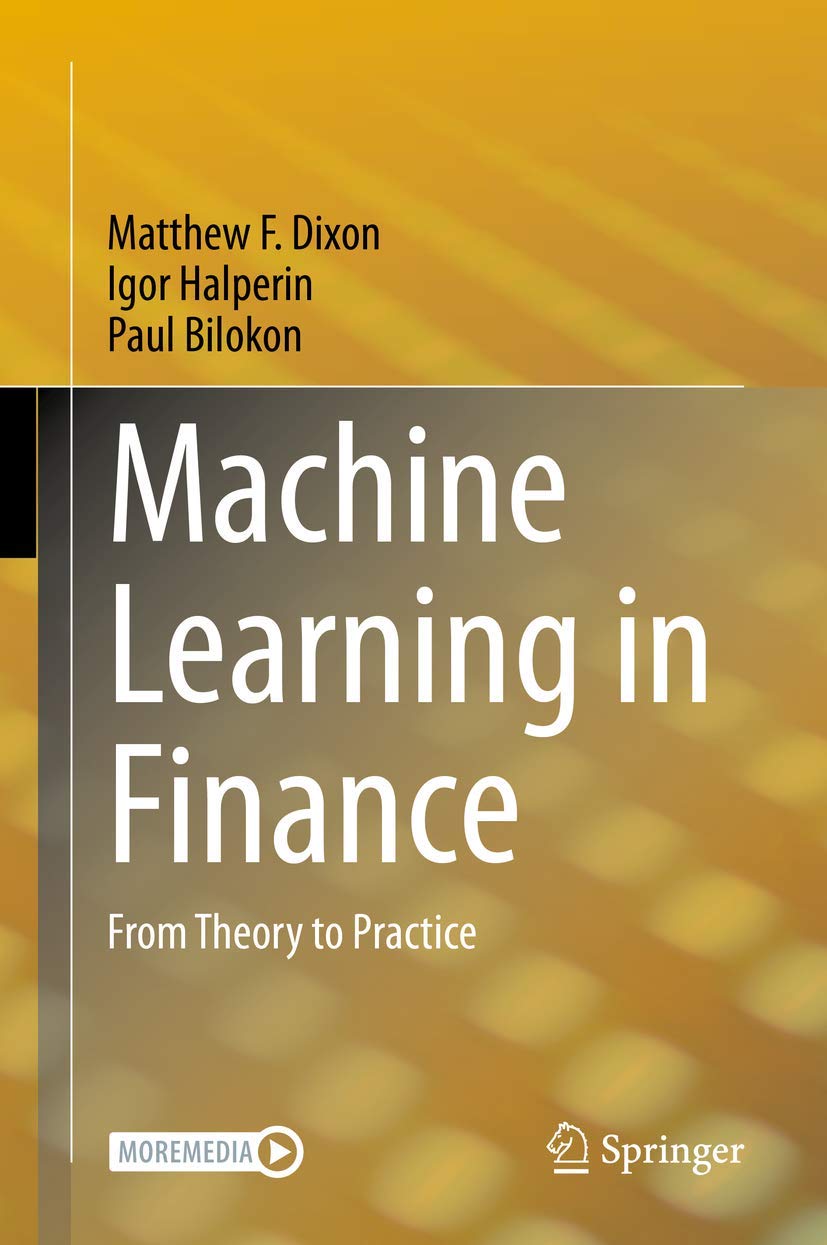
ler totalmente Machine Learning in Finance: From Theory to Practice
por Matthew F Dixon
Machine Learning in Finance: From Theory to Practice
This book introduces machine learning methods in finance. It presents a unified treatment of machine learning and various statistical and computational disciplines in quantitative finance, such as financial econometrics and discrete time stochastic control, with an emphasis on how theory and hypothesis tests inform the choice of algorithm for financial data modeling and decision making. With the trend towards increasing computational resources and larger datasets, machine learning has grown into an important skillset for the finance industry. This book is written for advanced graduate students and academics in financial econometrics, mathematical finance and applied statistics, in addition to quants and data scientists in the field of quantitative finance. Machine Learning in Finance: From Theory to Practice is divided into three parts, each part covering theory and applications. The first presents supervised learning for cross-sectional data from both a Bayesian and frequentist perspective. The more advanced material places a firm emphasis on neural networks, including deep learning, as well as Gaussian processes, with examples in investment management and derivative modeling. The second part presents supervised learning for time series data, arguably the most common data type used in finance with examples in trading, stochastic volatility and fixed income modeling. Finally, the third part presents reinforcement learning and its applications in trading, investment and wealth management. Python code examples are provided to support the readers' understanding of the methodologies and applications. The book also includes more than 80 mathematical and programming exercises, with worked solutions available to instructors. As a bridge to research in this emergent field, the final chapter presents the frontiers of machine learning in finance from a researcher's perspective, highlighting how many well-known concepts in statistical physics are likely to emerge as important methodologies for machine learning in finance.
Procurando Machine Learning in Finance: From Theory to Practice? Aqui você encontra tudo sobre este livro de Matthew F Dixon, publicado por Springer em 2 de julho de 2020. Nesta página estão a descrição da obra, os detalhes da edição (548 páginas) e os formatos disponíveis para baixar: pdf, epub, txt, djvu. Se você gosta de Livros Internacionais, Ciências Tecnológicas, Matemática, Aplicada, Probabilidade e Estatística, explore também outros títulos da mesma categoria no Encontrando os melhores livros. Veja ainda as outras obras de Matthew F Dixon em nosso catálogo.
Autores populares
Icon Group International (283) Publishing lmgdaw (250) Nikolay Krechet (145) Kennie B Journals (120) Charles Nehme (106) Riddler Books (105) webmarbook design (104) Mint and Cherry Notebooks (82) Jillo Trukudo (80) Ondrej Sarek (76) Iwona Makara (74) Just Visualize It (72) Moonpeak Library (69) Quick Witted Coconut (69) Mary Hirose (67) Talor Press (67) Various (67) Marina Buchholz B.Eng (58) Miller Sye (58) NAK Legal Publishing (58)Principais publicadores
Springer Independently published Forgotten Books Routledge Taschen Dover Publications Wiley Oxford University Press CRC Press Kessinger Publishing Princeton University Press Cambridge University Press Bloomsbury Academic O'Reilly Media Hal Leonard Publishing Corporation Tuttle Publishing Rizzoli International Publications Content provided by MemoryLane.com Editorial Tirant lo Blanch Thames & Hudson