Descrição do livro
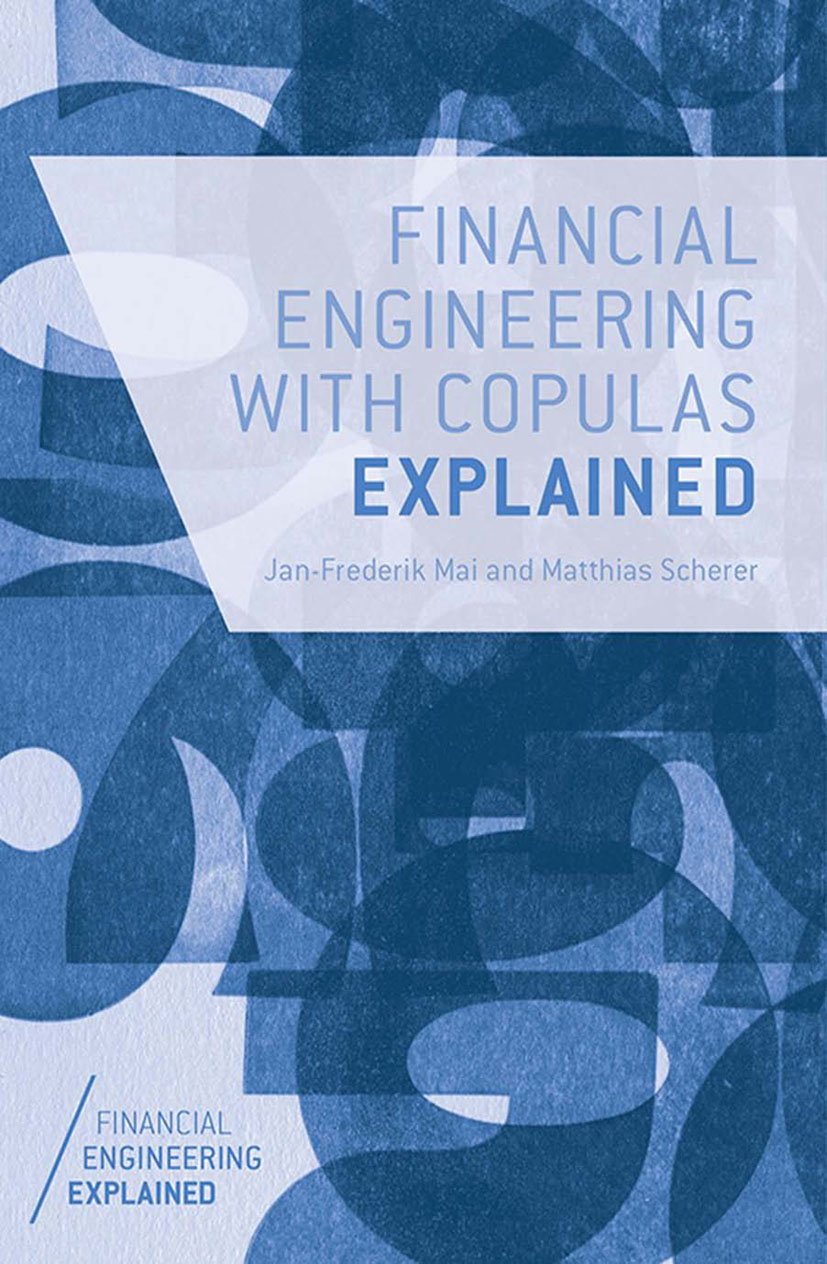
This is a succinct guide to the application and modelling of dependence models or copulas in the financial markets. First applied to credit risk modelling, copulas are now widely used across a range of derivatives transactions, asset pricing techniques and risk models and are a core part of the financial engineer's toolkit.
Isbn 13 :9781137346315
Encadernação :Kindle
Edição Financial Engineering with Copulas Explained (Financial Engineering Explained) (English Edition):2014ª
Livros recentes
Autores populares
Unknown Author (247) Barrett Williams (162) ChatGPT ChatGPT (123) Сергей Каледин (110) Lyudmil Tsvetkov (97) Sharifa McFarlane (79) Rodrigo B Santos (64) Kingston Publishing (63) YouGuide (58) animarueaidezain (51) Kurt Bai (48) Clayton Louis Turnage (47) keieisyakentoushikaken (47) Nikolay Krechet (47) NK Gosine (44) e-aizamiraiseisei (40) SHIZUOKANOSORATETSU (40) Valet WorkShop (36) Various (36) Evgeniia Naumchenko (34)Livros relacionados