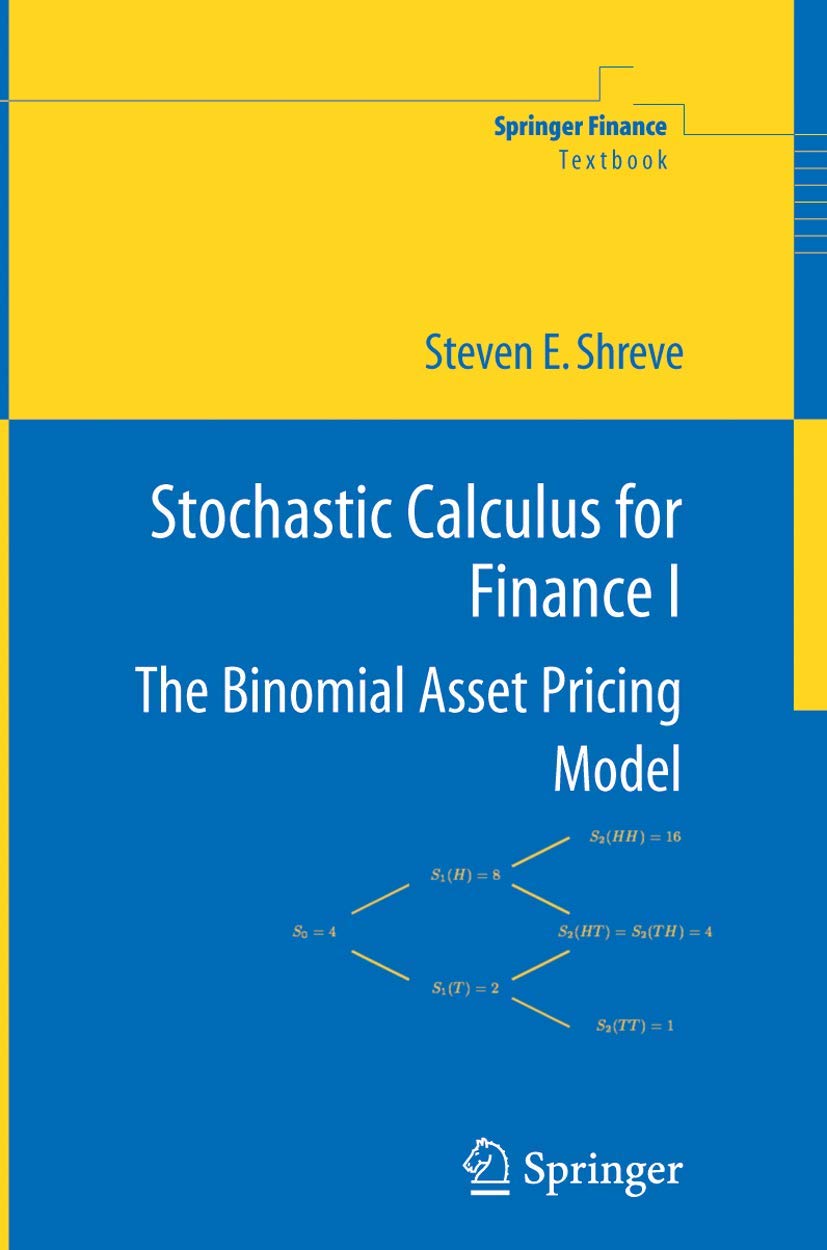
ler totalmente Stochastic Calculus for Finance I: The Binomial Asset Pricing Model
por Steven Shreve
Stochastic Calculus for Finance I: The Binomial Asset Pricing Model
Developed for the professional Master's program in Computational Finance at Carnegie Mellon, the leading financial engineering program in the U.S. Has been tested in the Exercises conclude every chapter; some of these extend the theory while others are drawn from practical problems in quantitative finance
classroom and revised over a period of several years
Procurando Stochastic Calculus for Finance I: The Binomial Asset Pricing Model? Aqui você encontra tudo sobre este livro de Steven Shreve, publicado por Springer Nature BV (Print-On-Demand) em 28 de junho de 2005. Nesta página estão a descrição da obra, os detalhes da edição (208 páginas) e os formatos disponíveis para baixar: pdf, epub, txt, djvu. Se você gosta de Livros Internacionais, Ciências Tecnológicas, Matemática, Matemática Pura, Cálculo, explore também outros títulos da mesma categoria no Encontrando os melhores livros. Veja ainda as outras obras de Steven Shreve em nosso catálogo.
Autores populares
Icon Group International (283) Publishing lmgdaw (250) Nikolay Krechet (145) Kennie B Journals (120) Charles Nehme (106) Riddler Books (105) webmarbook design (103) Mint and Cherry Notebooks (82) Jillo Trukudo (80) Ondrej Sarek (76) Iwona Makara (74) Just Visualize It (71) Moonpeak Library (69) Quick Witted Coconut (69) Mary Hirose (67) Talor Press (67) Various (67) Marina Buchholz B.Eng (58) Miller Sye (58) NAK Legal Publishing (58)Principais publicadores
Independently published Forgotten Books Routledge Taschen Dover Publications Wiley Oxford University Press CRC Press Kessinger Publishing Princeton University Press Cambridge University Press Springer Bloomsbury Academic O'Reilly Media Hal Leonard Publishing Corporation Tuttle Publishing Rizzoli International Publications Content provided by MemoryLane.com Editorial Tirant lo Blanch Thames & Hudson