Descrição do livro
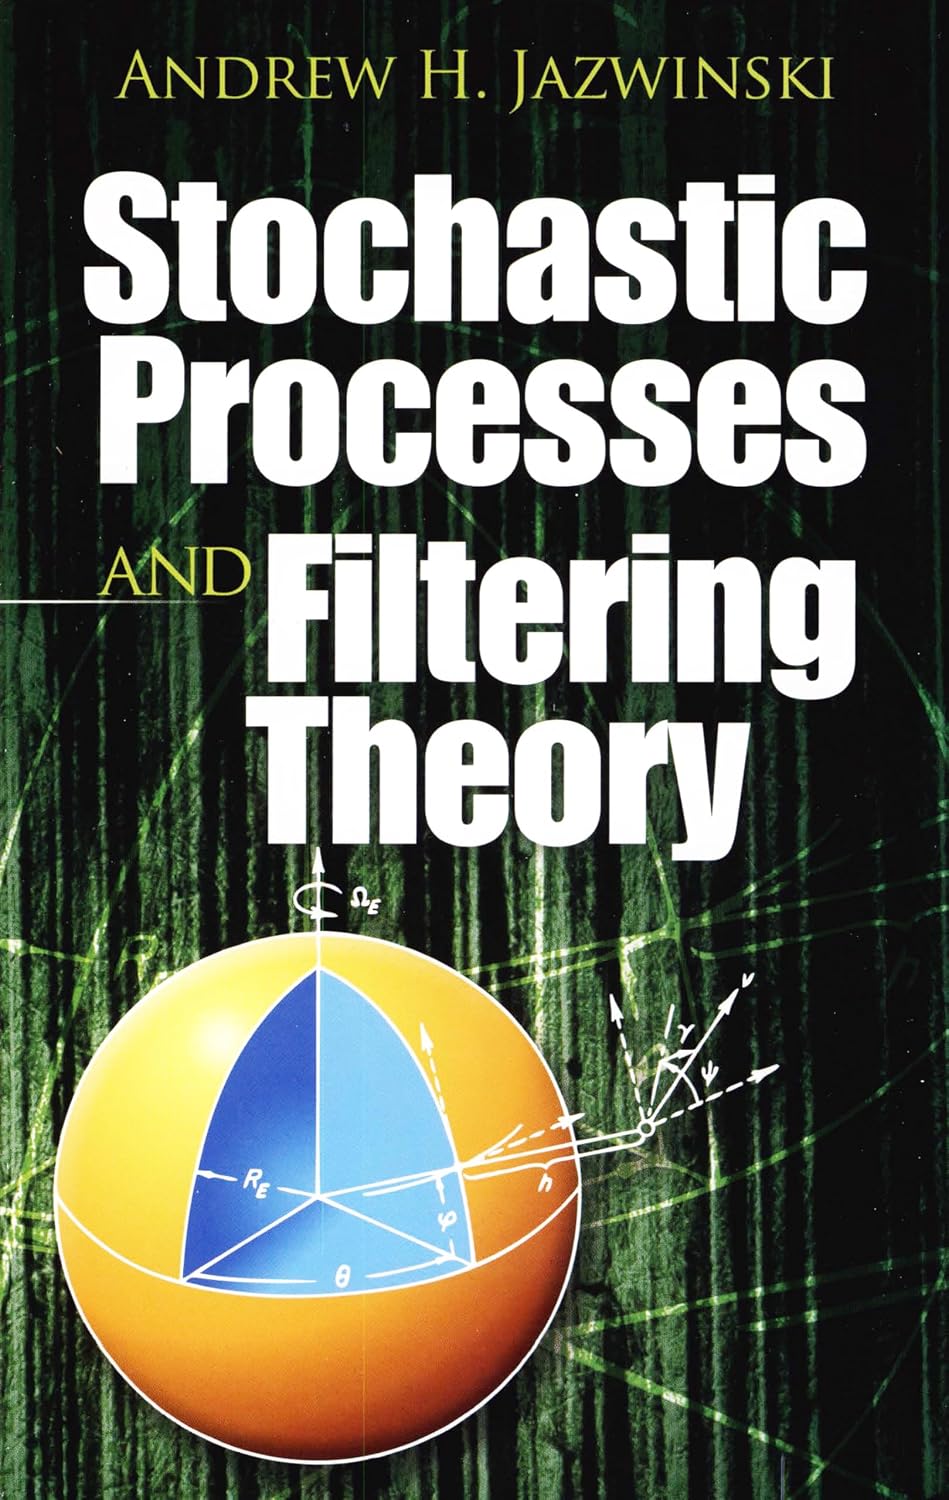
This unified treatment of linear and nonlinear filtering theory presents material previously available only in journals, and in terms accessible to engineering students. Its sole prerequisites are advanced calculus, the theory of ordinary differential equations, and matrix analysis. Although theory is emphasized, the text discusses numerous practical applications as well.
Taking the state-space approach to filtering, this text models dynamical systems by finite-dimensional Markov processes, outputs of stochastic difference, and differential equations. Starting with background material on probability theory and stochastic processes, the author introduces and defines the problems of filtering, prediction, and smoothing. He presents the mathematical solutions to nonlinear filtering problems, and he specializes the nonlinear theory to linear problems. The final chapters deal with applications, addressing the development of approximate nonlinear filters, and presenting a critical analysis of their performance.
Autores populares
Icon Group International (283) Publishing lmgdaw (250) Nikolay Krechet (145) Kennie B Journals (120) Charles Nehme (106) Riddler Books (105) webmarbook design (104) Mint and Cherry Notebooks (82) Jillo Trukudo (80) Ondrej Sarek (76) Iwona Makara (74) Just Visualize It (72) Moonpeak Library (69) Quick Witted Coconut (69) Mary Hirose (67) Talor Press (67) Various (67) Marina Buchholz B.Eng (58) Miller Sye (58) NAK Legal Publishing (58)